📊 Your Preapproval Says $500K. Should You Actually Spend $500K? 💳You finally talked with a lender.They reviewed your income.Credit.Debts.Finances.And you hear:“You're approved up to $500

Dated: December 29 2021
Views: 225
There are things that can happen to their homes that their homeowners insurance policies don't cover. Fire is the basic coverage provided by an insurance policy, while other common perils are water damage, theft, wind and liability. Earthquake and flood usually require a separate policy. In some states you can add earthquake coverage as an endorsement. It is important to discuss the risk you face and purchase the proper coverage. Just so you'll be forewarned, here are eight other perils, besides damage from an invading squirrel, for which you probably aren't insured.
Damage caused by flooding is excluded under standard homeowners insurance policies, according to the institute's primer on what disasters are covered by insurance. That's why it's prudent to obtain flood insurance, either from a private insurer or through the U.S. government's National Flood Insurance Program.
When a 5.8 magnitude earthquake in Virginia shook the U.S. east coast in 2011, it caused as much as $300 million in losses and varying degrees of damage to 600 residences. Many of the owners may have been chagrined to discover that their homeowners insurance didn't cover the cost of repairing the harm to their houses. Coverage for earthquakes, which can damage foundations and collapse walls, requires a separate policy, though a standard homeowners policy generally will cover damage from fires caused by quakes, according to the institute.
Sewer backups can be pretty messy, and they're not covered either by homeowners insurance policies or flood coverage, according to the institute. Instead, you'll need to purchase additional sewer coverage.
Maintenance damage. Homeowners policies don't cover damage caused to your home by your neglect of basic maintenance, according to the institute. Similarly, you're not covered if your house becomes infested by termites and other pests, or develops mold.
Sure, they're fun. But according to the National Association of Insurance Commissioners, both trampolines and pools are dangerous enough that some companies may not insure your property if you have them, or else may exclude liability for any injuries related to them. They also may even cancel your policy if you don't inform them when you get a trampoline or a pool, or don't follow the policy's safety guidelines.
If your family pet bites a visitor, you're typically covered for legal liability up to your policy's liability limit — usually $100,000 — according to the institute. The average dog bite claim is around $39,000, so you should be OK. But it's a bigger problem if you own a breed with a reputation for being aggressive, because some insurance companies won't cover you at all.
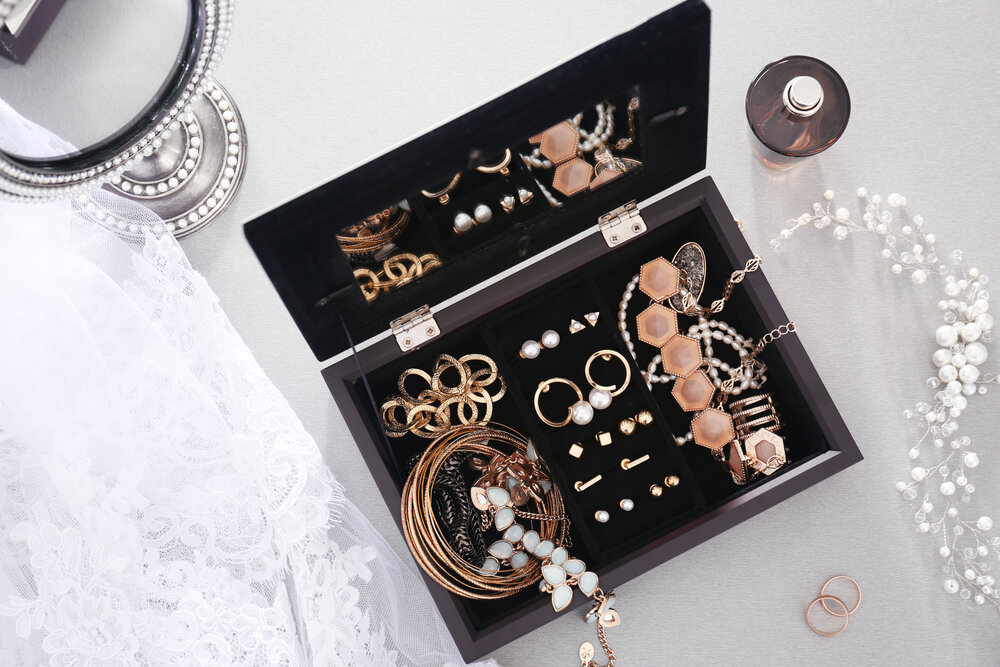
Typically, homeowners' policies set a limit on how much bling they'll cover — usually around $1,500, according to the institute's article on jewelry and other valuables. If you've got a lot of costly rings or necklaces, you'll want to consider getting a floater policy, which covers any sort of loss, including dropping your ring down a drain. That'll require you to get the items appraised professionally.
If you've got a friend or neighbor who allows you to store some of your possessions in his or her basement, you could lose out in the event of a disaster, according to Amy Bach, executive director of United Policyholders, a California-based consumer advocacy group. That person's insurer isn't going to cover your losses, since you're not the homeowner. "You'd have to try to collect money from your friend," Bach says.
My name is Jamie DeBrosse and I am a REALTOR® in the Cherry Creek School district and surrounding cities. My real estate expertise is partnering with Denver, Colorado area home sellers to strategical....
📊 Your Preapproval Says $500K. Should You Actually Spend $500K? 💳You finally talked with a lender.They reviewed your income.Credit.Debts.Finances.And you hear:“You're approved up to $500
If you’ve ever bought a home in a community with a homeowners association, you already know there can be a lot more to the transaction than simply finding the right house.HOA documents,
💵 You Have $20,000 to Prepare Your Home for Sale — Where Should You Actually Spend It? 🤔Let's play a hypothetical game.You're planning to sell your home.And you've decided you're
By Melanie Hood, RealtorHomeowners associations can be a source of frustration—or one of the reasons a neighborhood remains attractive and well maintained.The difference often isn't simply
 The content relating to real estate for sale in this Web site comes in part from the Internet Data eXchange (IDX) program of METROLIST, INC., DBA RECOLORADO©. Real estate listings held by brokers other than EXIT Realty, A Smart Move are marked with the IDX Logo. This information is being provided for the consumers' personal, non-commercial use and may not be used for any other purpose. All information subject to change and should be independently verified. September 25, 2026 7:44 PM UTCd
1. This publication is designed to provide information regarding the subject matter covered. It is displayed with the understanding that the publisher and authors are not engaged in rendering real estate, legal, accounting, tax, or other professional services and that the publisher and authors are not offering such advice in this publication. If real estate, legal, or other expert assistance is required, the services of a competent, professional person should be sought.
2. The information contained in this publication is subject to change without notice.
METROLIST, INC., DBA RECOLORADO MAKES NO WARRANTY OF ANY KIND WITH REGARD TO THIS MATERIAL, INCLUDING, BUT NOT LIMITED TO, THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE. METROLIST, INC., DBA RECOLORADO SHALL NOT BE LIABLE FOR ERRORS CONTAINED HEREIN OR FOR ANY DAMAGES IN CONNECTION WITH THE FURNISHING, PERFORMANCE, OR USE OF THIS MATERIAL.
3. PUBLISHER'S NOTICE:
All real estate advertised herein is subject to the Federal Fair Housing Act and the Colorado Fair Housing Act, which Acts make it illegal to make or publish any advertisement that indicates any preference, limitation, or discrimination based on race, color, religion, sex, handicap, familial status, or national origin.
4. METROLIST, INC., DBA RECOLORADO will not knowingly accept any advertising for real estate that is in violation of the law. All persons are hereby informed that all dwellings advertised are available on an equal opportunity basis.
5. 
6. © 2026 METROLIST, INC., DBA RECOLORADO© - All Rights Reserved
6455 S. Yosemite St., Suite 500
Greenwood Village, CO 80111 USA
7. ALL RIGHTS RESERVED WORLDWIDE. No part of this publication may be reproduced, adapted, translated, stored in a retrieval system or transmitted in any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the publisher. The information contained herein including but not limited to all text, photographs, digital images, virtual tours, may be seeded and monitored for protection and tracking.
Options
Show More...
 The real estate listing information and related content displayed on this site is provided exclusively for consumers’ personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. This information and related content is deemed reliable but is not guaranteed accurate by elevateMLS.
